 ▶
 ▶
Retirement Drawdown Command Center
Saving was the easy part. Spending it down is the math.
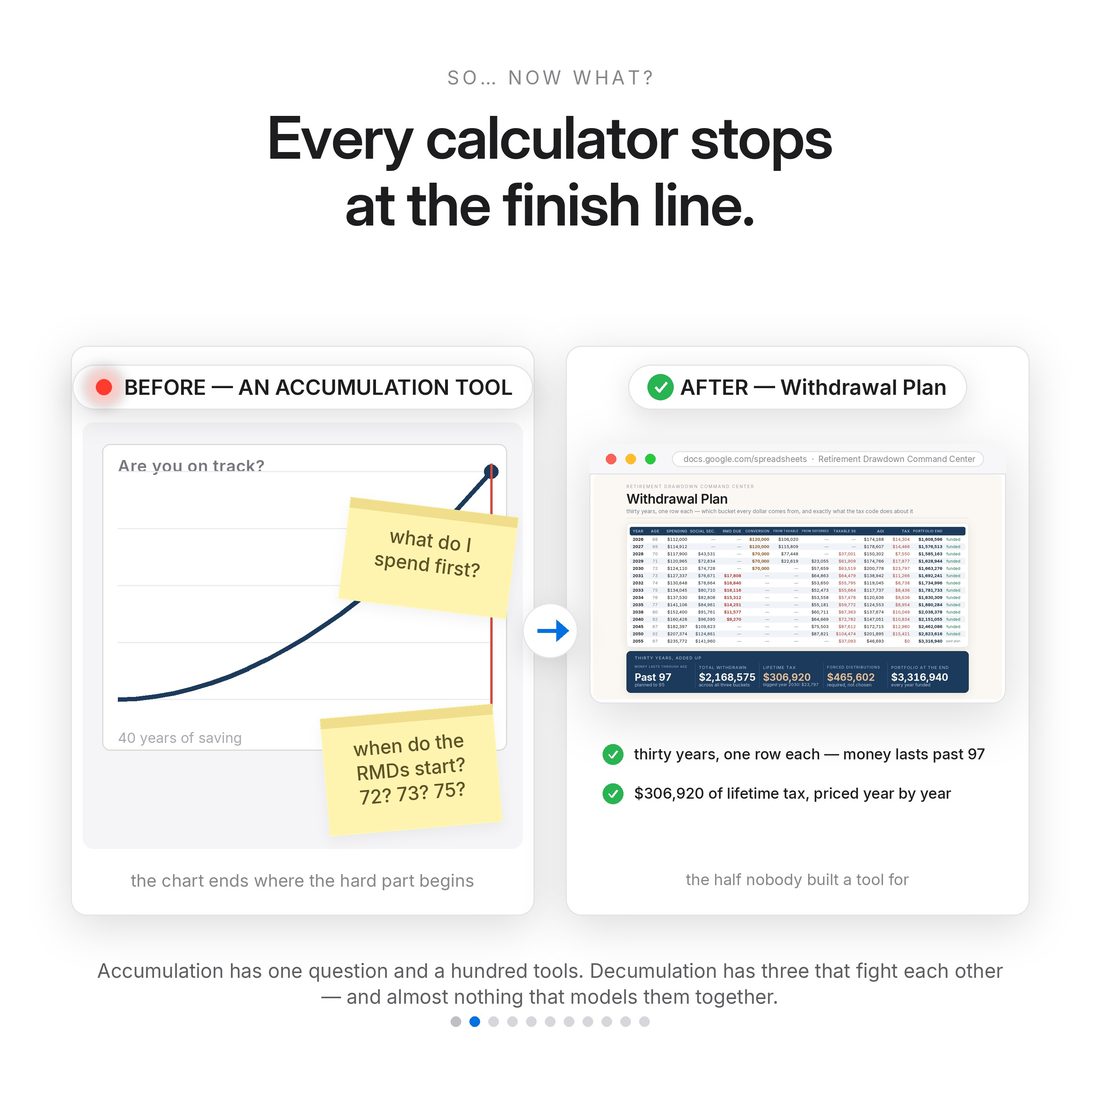
5.0shop rating · 6 Etsy reviewsSaving was the easy part. Spending it down is the math. Every retirement spreadsheet you can buy answers one question: am I on track. This one starts on the day the paycheck stops — because that is where three forces collide. Required minimum distributions force income out at 73 or 75 depending on your birth year. Social Security is taxed against thresholds unchanged since 1984. And the order your returns arrive in decides whether the same average lasts thirty years or nineteen. This 14-tab file models all three, together, for thirty years, and prices every decision in dollars.
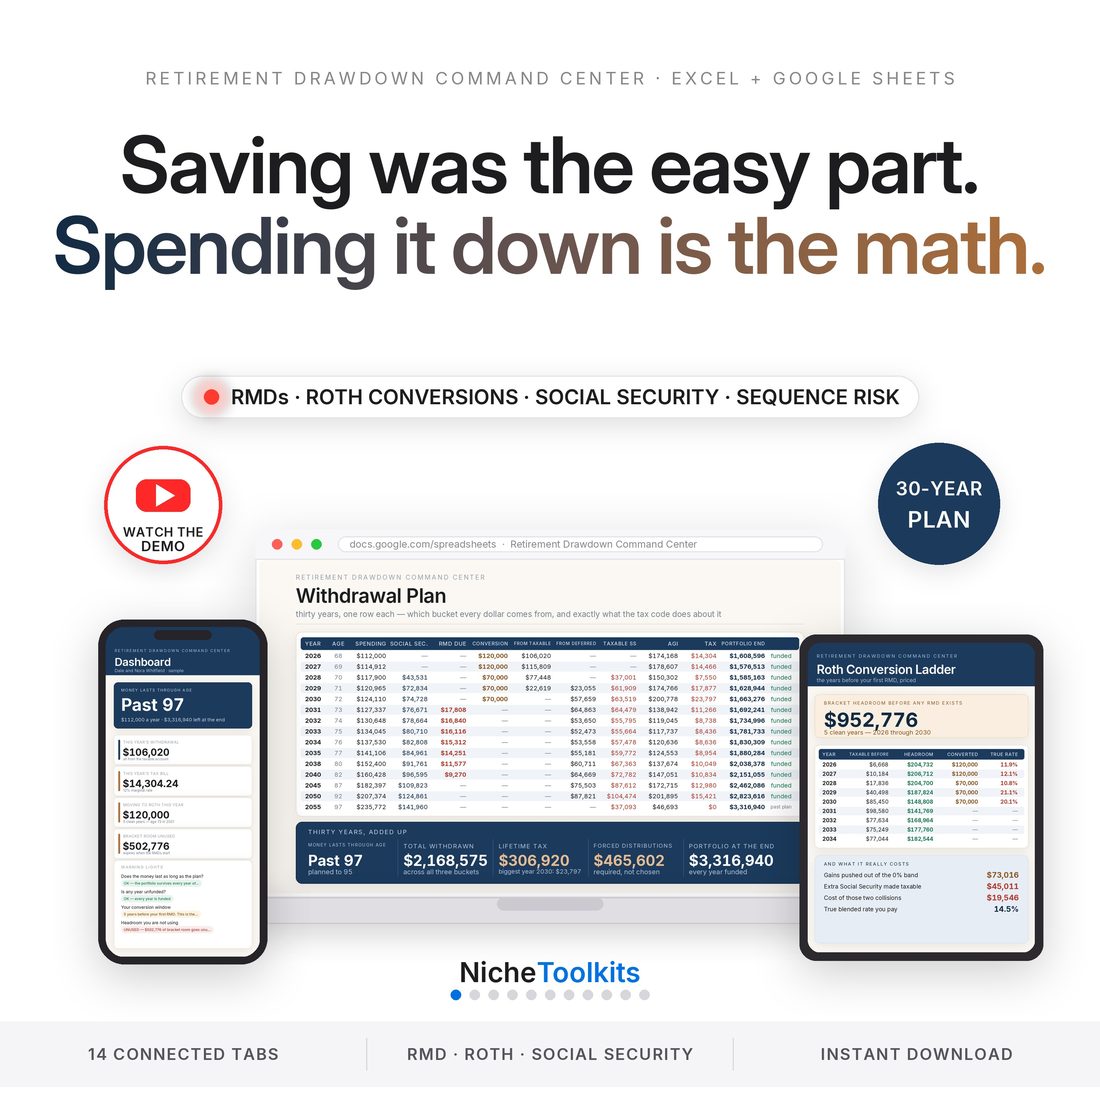
- Withdrawal Plan — thirty years, year by year, one row to follow
- RMD Schedule — the real applicable ages (73 and 75), per spouse, per cohort
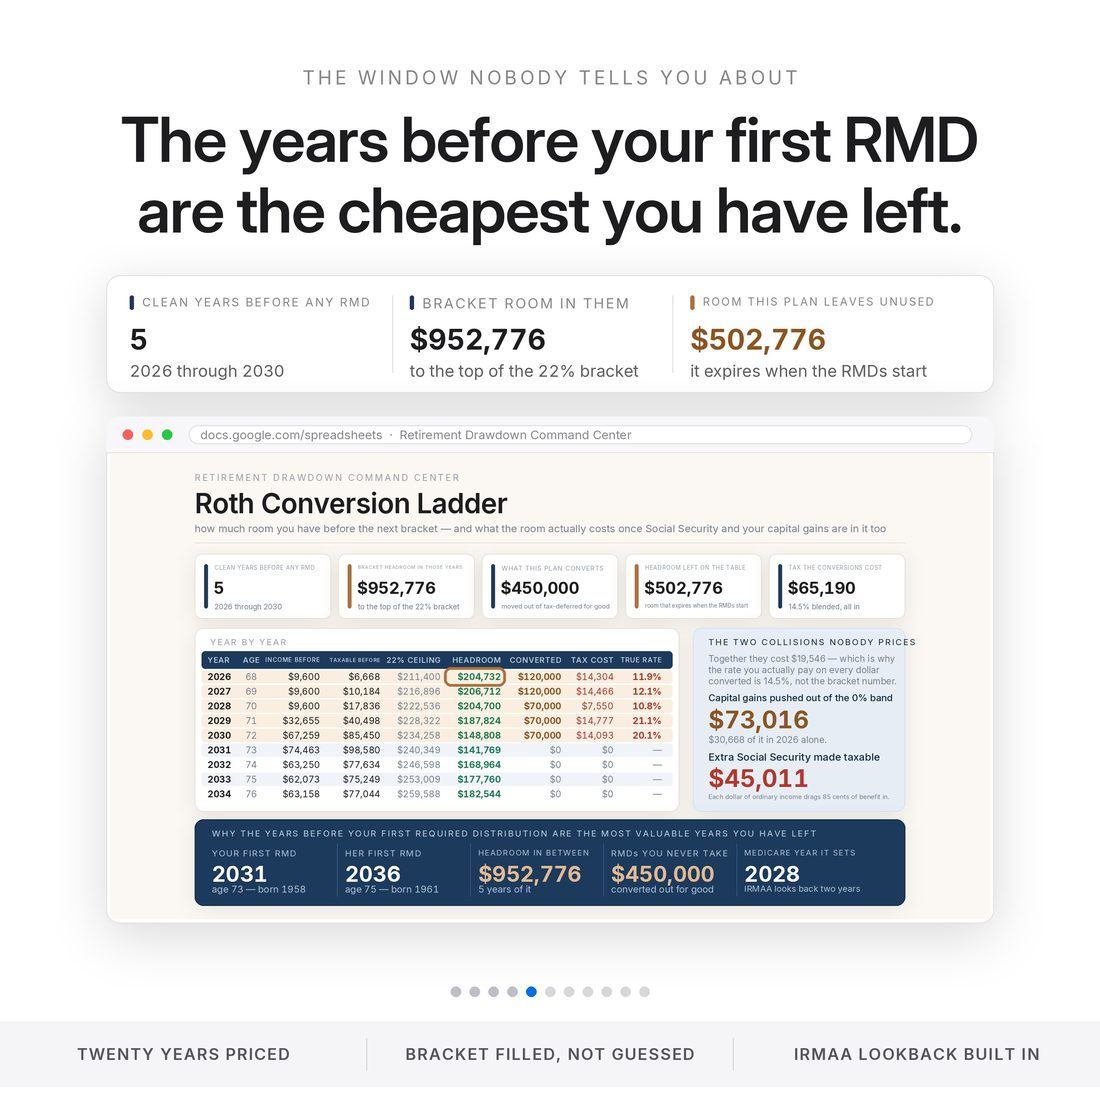
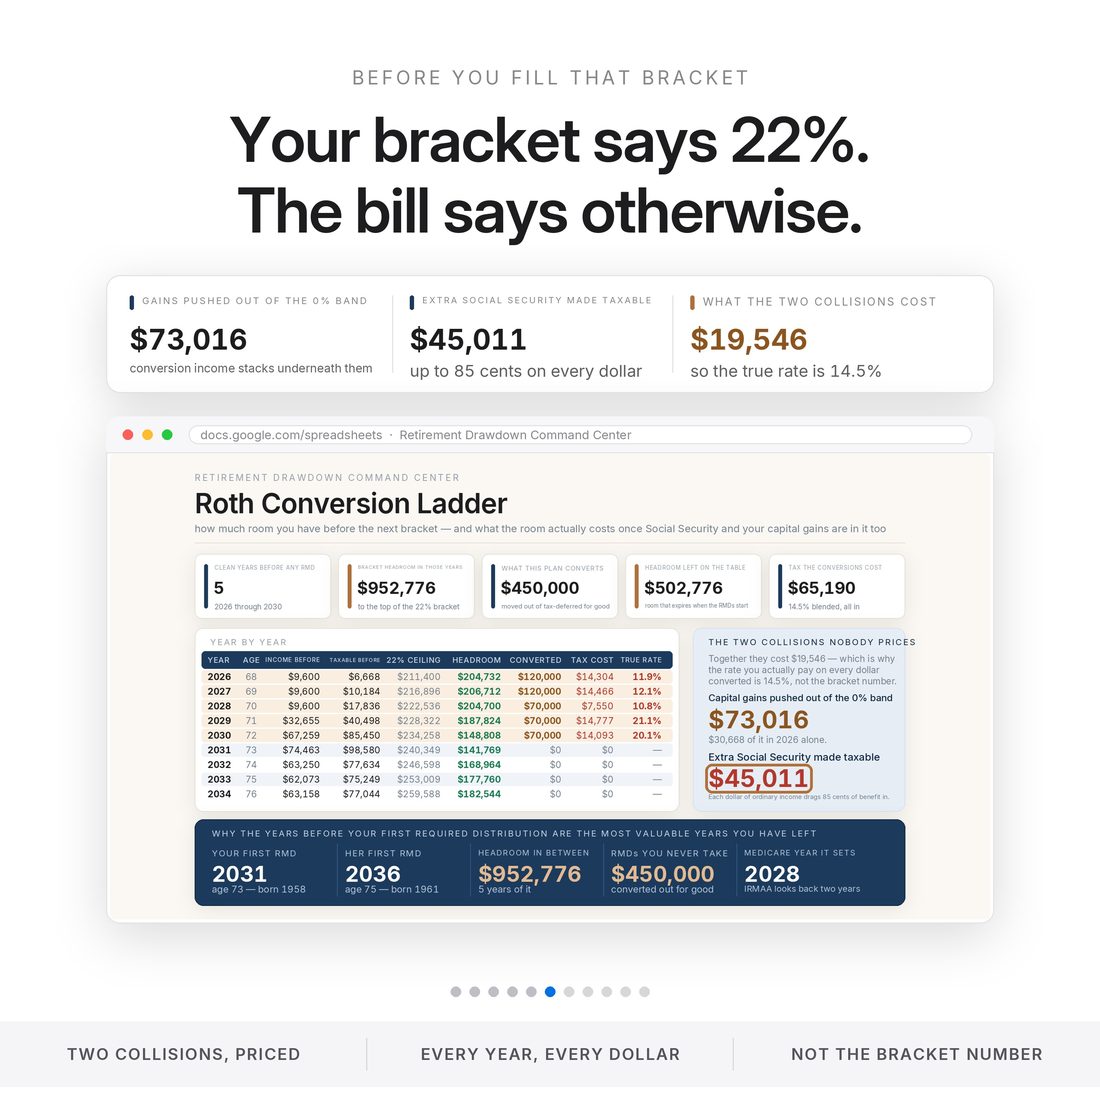
- Roth Conversion Ladder — priced at the true blended rate, not the bracket
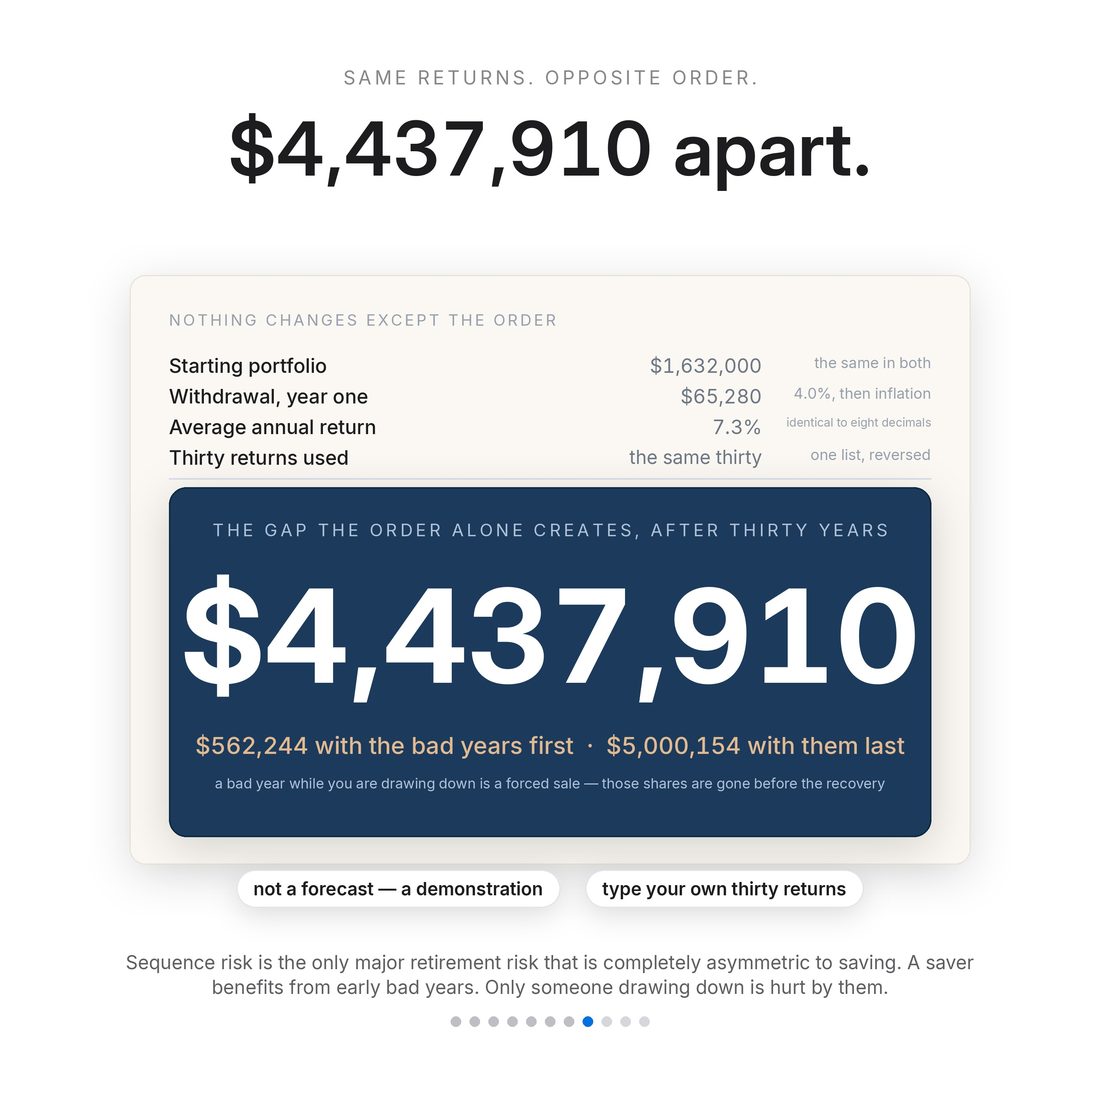
- Sequence Risk — the same returns reordered, and what that does to the ending balance
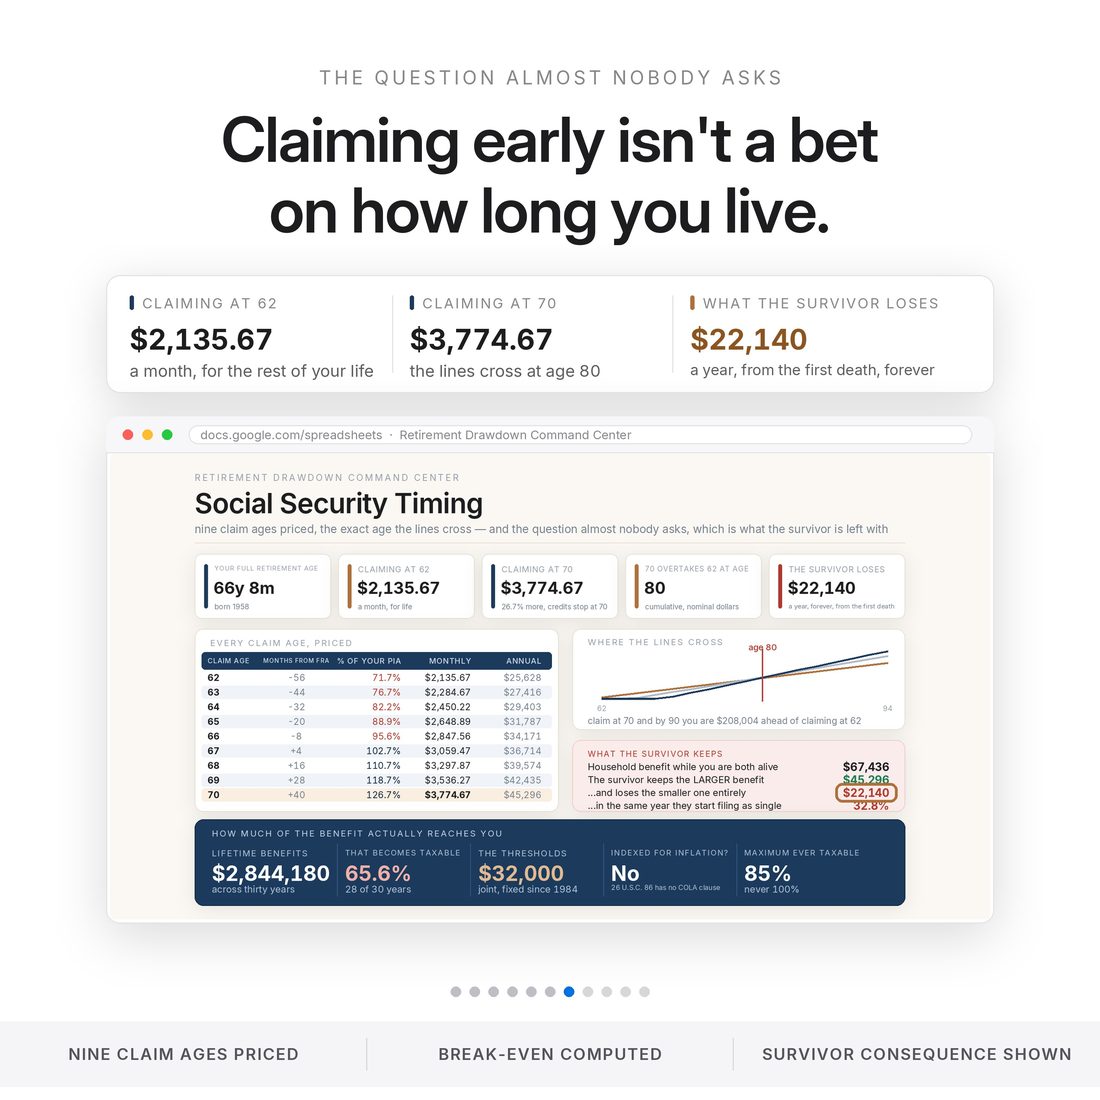
- Social Security Timing — claim ages priced against the frozen thresholds
Overview
Saving was the easy part. Spending it down is the math.
Every retirement spreadsheet you can buy answers one question: am I on track. This one starts on the day the paycheck stops — because that is where three forces collide. Required minimum distributions force income out at 73 or 75 depending on your birth year. Social Security is taxed against thresholds unchanged since 1984. And the order your returns arrive in decides whether the same average lasts thirty years or nineteen. This 14-tab file models all three, together, for thirty years, and prices every decision in dollars.
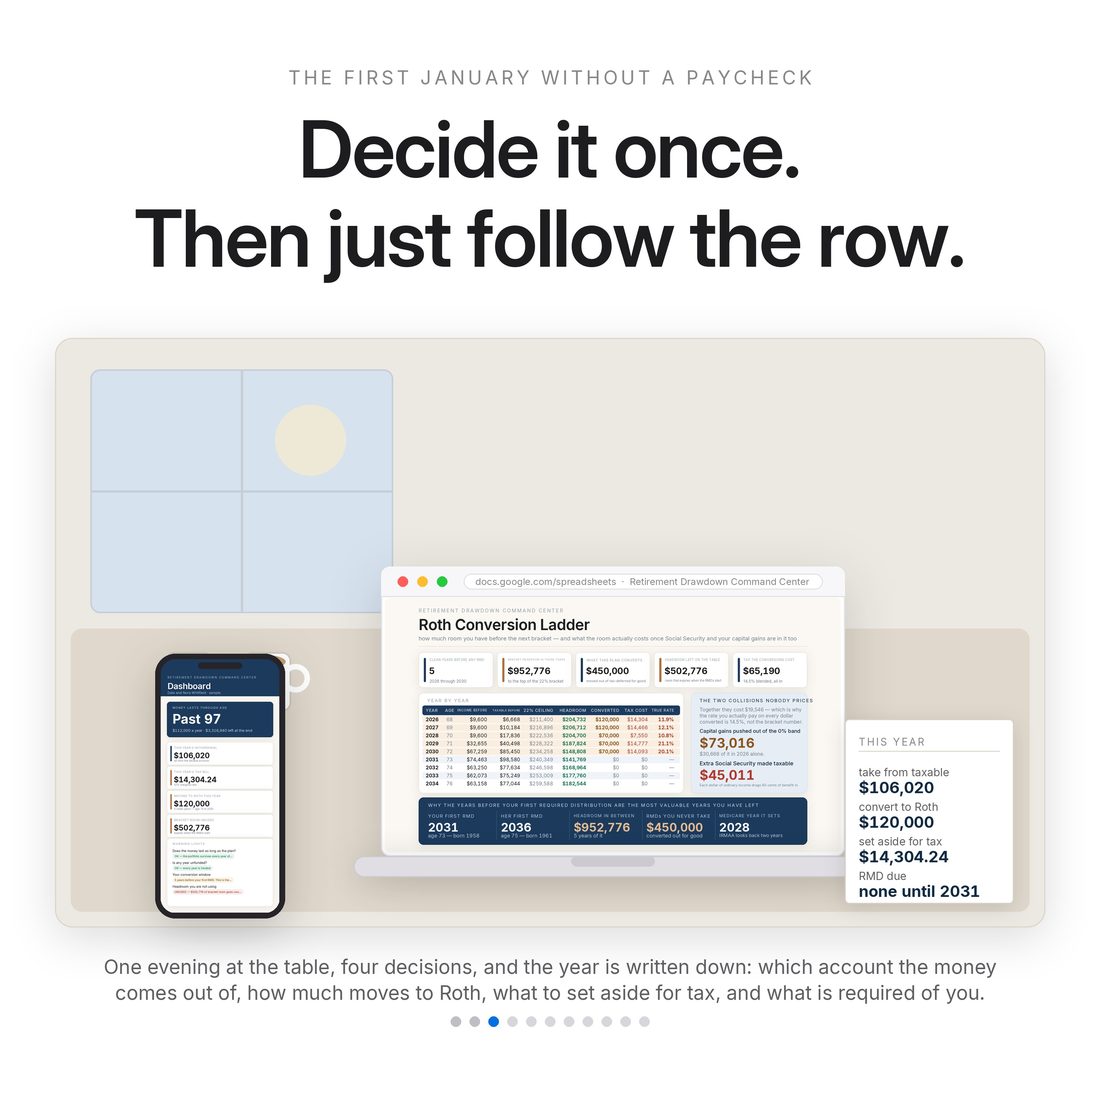
Decide it once. Then just follow the row.
What's Included
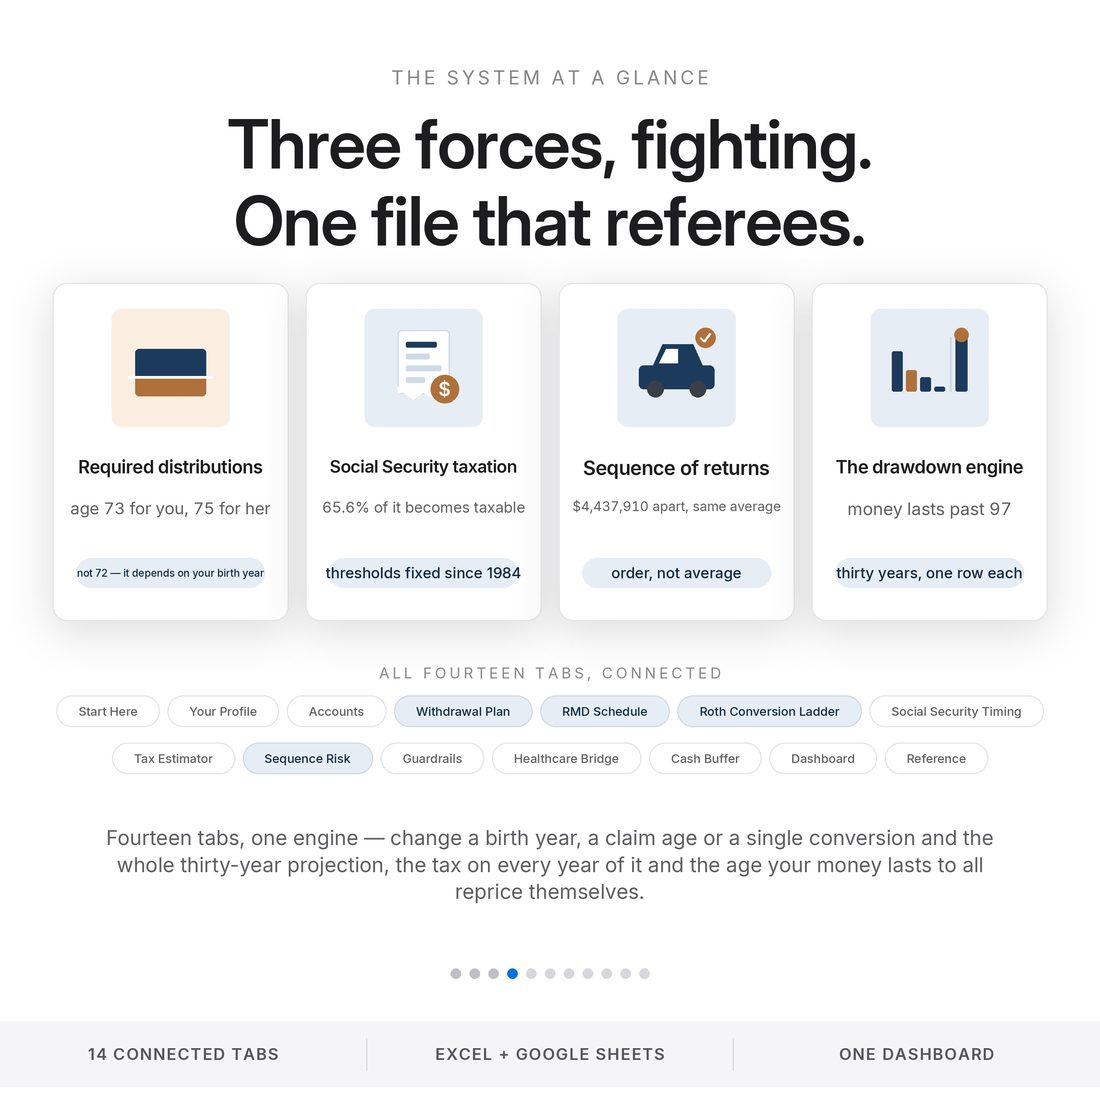
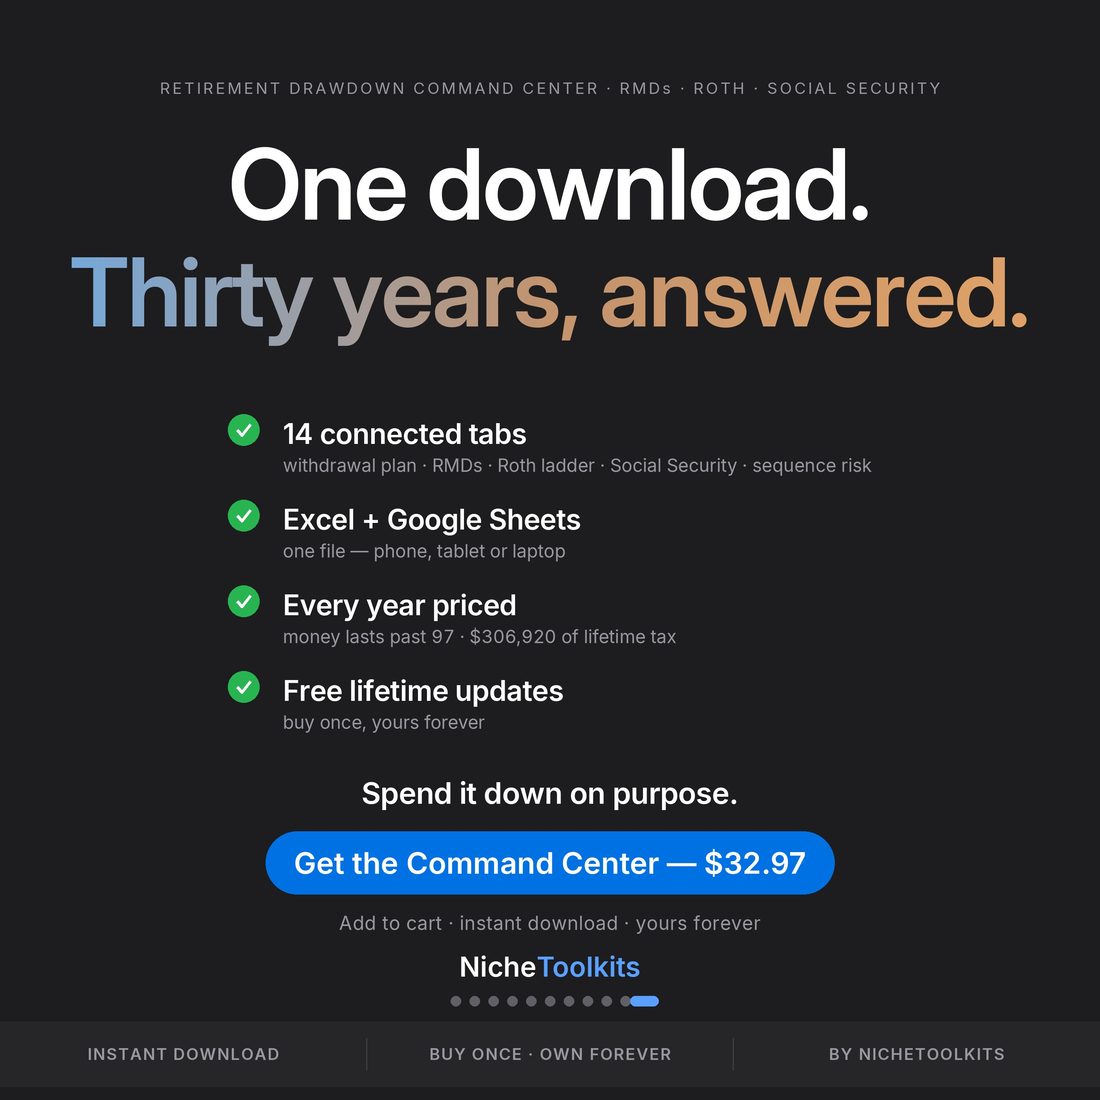
14 connected tabs:
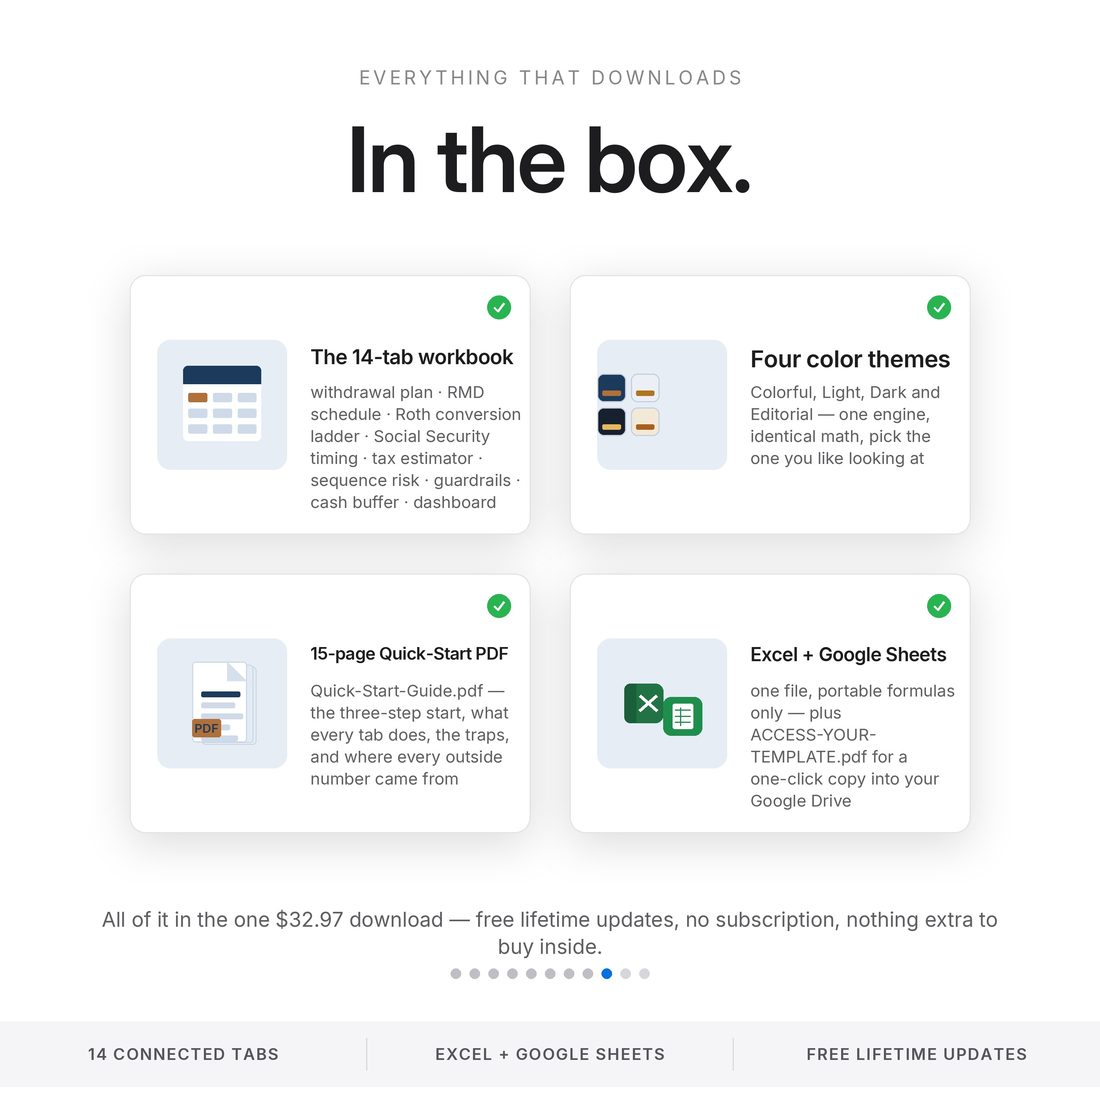
- Retirement-Drawdown-Command-Center.xlsx — the 14-tab engine (Excel + Google Sheets)
- Bonus Themes folder — the same workbook in Light, Dark and Editorial
- Quick-Start-Guide.pdf + ACCESS-YOUR-TEMPLATE.pdf — one-click Google Sheets access + the video tutorial link
- README + LICENSE — delivered as one ZIP, instant download
Key Benefits
Why this one
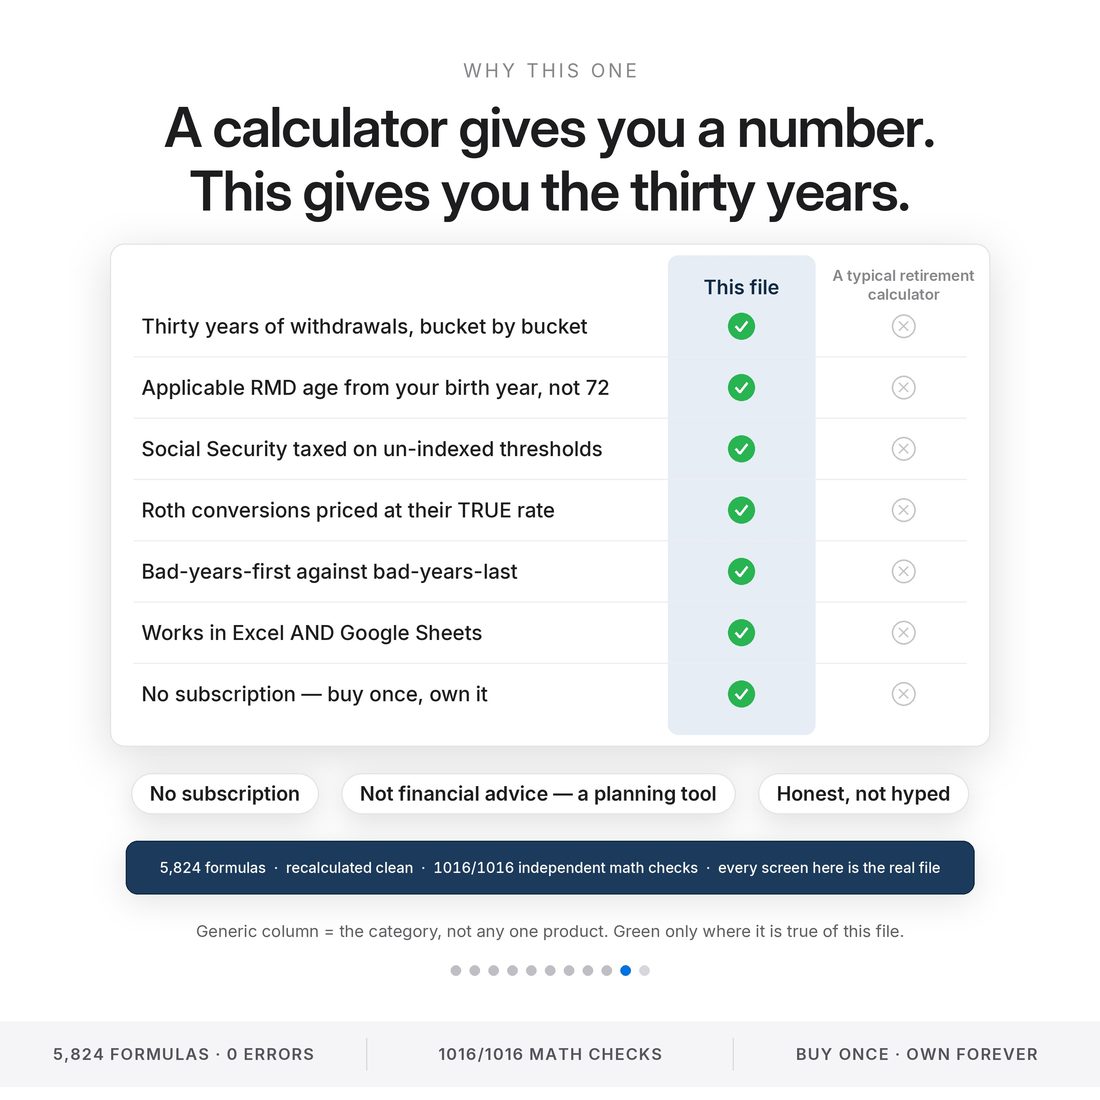
Born 1958 means RMDs at 73; born 1961 means 75. One household can be in two cohorts — the file knows, per person.
A Roth conversion's true cost isn't the bracket: the sample year reads 22% but blends to 14.5% — and one year hits 21.1% — once capital-gains displacement and Social Security taxation are counted.
Identical returns averaging 7.3%: bad years first leaves $562,244, bad years last leaves $5,000,154. Sequence risk, drawn in dollars.
Provisional-income lines never got a COLA — every year of inflation taxes more of your benefit. The estimator shows it happening.
Spending rules ship with their real triggers and their real limits — no magic percentages presented as guarantees.
Take half of each year’s spending from savings and half from the 401(k) — or as much as an ACA subsidy line, an IRMAA tier or a bracket top allows, solved to the dollar. When one account runs dry the plan switches on its own and says which year it had to.
5,824 formulas · recalculated clean · 1016/1016 independent math checks. Every image is the real file.
Who It's For
Built for
- Recent retirees and those retiring within five years
- Couples with two birth years — and therefore two RMD ages
- Anyone with a large traditional IRA or 401(k) staring at a first RMD
- Anyone deciding when to claim Social Security — or helping a parent decide
How It Works
Up and running in minutes
The ACCESS-YOUR-TEMPLATE.pdf in your download opens a copy in Google Sheets with one click
Two birth years, accounts by type, benefit estimates — the cohorts sort themselves
Claim ages, conversion sizes, spending guardrails — each priced in dollars
Sequence Risk reorders the same returns and shows the spread
The Withdrawal Plan turns it into one row per year you can actually follow
Why It's Different
Not another template
Accumulation trackers ask if you're on track. This is the other side: RMD cohorts by birth year, the two-year IRMAA lookback, conversions at their blended rate, sequence risk in dollars. The math of the spending years, done properly, once.
Delivery & Compatibility
Instant, and works with what you use
As soon as your order is complete you get instant access to download your files. Prefer Google Sheets for real-time updates and dropdowns? It's fully optimized. More comfortable in Excel? It works just as well.
Built and tested in the latest Excel (Office 365). On Mac we recommend the Google Sheets version — the template is not compatible with Apple Numbers. Available in English. The template ships with sample data so every screen works on open; clear it whenever you're ready. The images and video show that sample data to demonstrate how it looks in use.
FAQ
Questions, answered
Does it work in Google Sheets?
Yes — one click: the ACCESS-YOUR-TEMPLATE.pdf in your download opens a copy straight into Google Sheets. The .xlsx works in Excel too.
Which RMD age does it use?
Both — 73 for those born 1951–1958, 75 after 1959, per spouse. (The 1959 cohort is literally reserved in the final regulations; the file says so rather than guessing.)
Does it tell me when to claim Social Security?
It prices your options honestly — including how the frozen thresholds tax each path — and leaves the decision where it belongs: with you.
Is the 4% rule in here?
Guardrail strategies ship with their real triggers and limits. No success percentages are printed as promises.
Is anything pre-loaded?
Sample data (Dale and Nora's thirty years) ships inside so every screen works on open — clear it when you're ready.
Can I get a refund on a digital download?
Because delivery is instant, all sales are final — but message us with any issue and we'll make it right.
This is a planning tool, not tax, investment or financial advice. Confirm every figure with your tax professional or advisor before acting — especially conversions and claiming decisions. For personal use only. © 2026 NicheToolkitHub — no resale or redistribution.